August, 2026
Home › FinTech & Modern Money Tools › Neobanks & Digital Banking Platforms › Current Bank Review
This review is part of our Neobanks & Digital Banking Platforms cluster, covering how digital-first banking platforms compare so you can build the right structure for your money.
About the Author
Ally M. Scott is a personal finance advisor with 22+ years of experience, focused on helping Millennials and Gen Z build credit intelligently and escape debt cycles. She covers credit strategy, banking systems, and financial infrastructure at PersonalOne.org -- where the goal is always systems over willpower.
What You Need to Know -- Current at a Glance
Current is a New York-based neobank built with Millennials and Gen Z in mind. It offers no-fee checking, early direct deposit, high-yield savings pods, and a points rewards system on debit spending. It is a solid entry-level neobank with a clean app experience -- but its savings yield and feature depth trail some competitors when direct comparison matters.
-- Best for: Gen Z and younger Millennials who want a simple, app-first banking experience with goal-based savings pods
-- Not ideal for: Anyone prioritizing the highest savings yield, full-service banking, or credit building tools
-- Savings APY: Available on savings pods -- verify current rate at Current.com
-- Fees: No monthly fees on the basic account, no minimum balance requirements
-- FDIC insured: Yes -- through Choice Financial Group and Cross River Bank
-- Affiliate disclosure: PersonalOne is not an affiliate of Current. This review is independent and not compensated.
This Current bank review covers a neobank that launched in 2015 with a focus on teens and young adults -- it was one of the first neobanks to offer a teen banking account with parental controls -- and has since expanded its product to serve a broader young adult audience. Today, Current positions itself as a full checking and savings solution for people who want a modern banking experience without the friction of a traditional institution. If you're comparing options as a student specifically, Best Neobanks for Students in 2026 covers how Current stacks up against the rest of the field.
Like Chime, Current is not a bank in the legal sense. It is a financial technology company that delivers banking services through partner banks -- currently Choice Financial Group and Cross River Bank -- both of which carry FDIC insurance. Deposits held through Current are insured up to $250,000 per depositor through those partner institutions.
This review evaluates Current's core banking products for the adult account holder -- checking, savings pods, overdraft coverage, and the features that shape the day-to-day experience -- to help you determine whether Current belongs in your banking structure and in what capacity.
Where Current Fits in the Neobank Landscape
Current is one of several digital-first banking options worth understanding before making a decision. The FinTech & Modern Money Tools hub compares the full landscape -- neobanks, budgeting apps, and robo-advisors -- and how to assign the right tool to each role in your banking structure.
Current is a strong product in specific situations and a weak fit in others. Knowing which situation you are in changes how you evaluate it.
Current Checking and Savings: How the Accounts Work
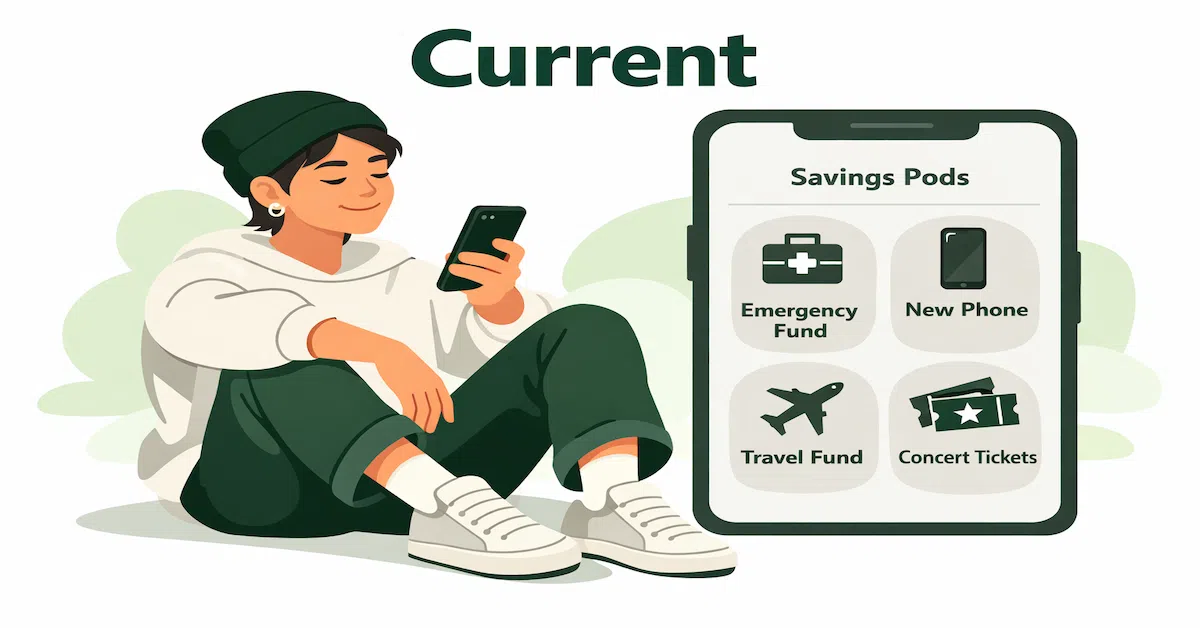
Current offers a spending account and up to three savings pods, all managed within a single app. Savings pods are goal-based savings buckets -- labeled and earmarked for specific purposes -- rather than a single pooled savings balance. This structure is designed to make saving feel intentional rather than abstract.
Spending Account: Standard Neobank Features, Clean Execution
Current's spending account has no monthly fee and no minimum balance requirement. Early direct deposit releases funds up to two days ahead of the standard settlement date, consistent with most neobanks. Overdraft coverage -- called Overdrive -- provides fee-free overdraft protection of up to $200 for qualifying members who receive regular direct deposits. The coverage amount is determined by account history and deposit patterns.
Current uses the Allpoint ATM network for fee-free cash withdrawals -- approximately 40,000 ATMs across the U.S. Out-of-network withdrawals carry a fee. Compared to Chime's 60,000-ATM footprint or SoFi's 55,000-ATM network, Current's ATM availability is somewhat narrower, which can matter depending on geography.
Savings Pods: Goal-Based Saving With an APY
Current's savings pods earn interest and can be labeled for specific goals -- emergency fund, vacation, car repair, down payment. Having up to three separate labeled buckets with their own balances creates a more tangible savings experience than a single undifferentiated savings balance. For people who benefit from seeing their progress toward specific goals rather than tracking a combined number, this structure has real behavioral value.
The APY on savings pods is available but not always at the top of the competitive high-yield savings market. As with all neobank savings rates, verify the current rate directly at Current.com before making a decision -- rates move with Federal Reserve policy and shift across institutions over time.
Points Rewards on Debit Spending
Current offers a points rewards system on debit card purchases at participating merchants. Points can be redeemed for cash back applied to the spending account. The rewards rate and participating merchant list vary and are not as robust as rewards credit cards -- but for someone who is not yet using a credit card for everyday spending, earning any return on debit purchases is a marginal improvement over a standard debit account with no rewards.
Cash Deposits: Same Limitation as Most Neobanks
Current does not accept direct cash deposits. Cash can be deposited through participating retailers in the Green Dot network, with fees typically set by the retailer. This is the same limitation that applies to most neobanks and remains a real constraint for anyone whose income includes regular cash handling.
Where Current Performs Well
Goal-Based Savings Structure
The savings pods system is Current's most distinctive feature. Having separate, labeled savings buckets -- each earning interest independently -- makes it easier to mentally assign saved money to specific purposes without the funds running together in a single balance. For someone building an emergency fund while simultaneously saving for a car repair or a planned expense, the pods structure provides clarity that a single savings account does not.
Overdrive Overdraft Coverage
Overdrive provides up to $200 in fee-free overdraft coverage for qualifying members -- a higher ceiling than Chime's SpotMe starting limit of $20-$50. For members who occasionally run close to their balance, the higher coverage amount reduces the risk of a small shortfall triggering a declined transaction or cascading financial disruption.
App Experience and Ease of Use
Current's app is consistently rated among the cleaner and more intuitive digital banking experiences available. For users who will manage their banking entirely from a mobile device, the quality of the app interface is a functional consideration -- not just aesthetics. A confusing dashboard or unreliable app creates friction that accumulates over time.
Where Current Falls Short
No Credit Building Tool
Unlike Chime -- which offers the Credit Builder secured card -- Current does not have a dedicated credit building product integrated into its banking platform. For users who need to build or rebuild credit alongside their banking, Current requires going elsewhere for a credit product, adding a step that Chime handles within a single platform.
Savings Yield Not Consistently Top-Tier
Current's savings pod APY is meaningful but has not consistently ranked among the highest available in the high-yield savings market. For users whose primary goal is maximizing the return on their savings, Current's rate should be compared directly against competitors -- including SoFi with direct deposit, Marcus, and Ally -- before deciding.
Narrower ATM Network
With approximately 40,000 fee-free ATMs through Allpoint, Current's ATM footprint is smaller than Chime's 60,000-ATM network or SoFi's 55,000-ATM access. In major metropolitan areas this difference is rarely felt. In smaller markets and suburban areas, the gap can mean more frequent out-of-network withdrawals and the fees that come with them.
No Bank Charter
Like Chime, Current operates through partner banks rather than holding its own charter. FDIC insurance applies through those partner institutions, but the dependency on banking partnerships is a layer of structural complexity that institutions with their own charters do not have. This matters most if a banking partner relationship changes -- an unlikely but not impossible scenario.
Who Current Is Right For
Current Is a Strong Fit If:
You want goal-based saving with visual structure. The savings pods system is genuinely useful for people who benefit from mentally separating their savings into labeled categories rather than tracking a single undifferentiated balance.
You want higher overdraft coverage than Chime's starting limit. Overdrive's up to $200 ceiling provides more buffer for members who occasionally run close to their balance.
You want a clean, modern app experience as a primary banking interface. Current's app design is consistently rated well and makes day-to-day banking straightforward.
You are a younger adult opening your first real checking account. Current's product is well-suited to someone entering independent banking for the first time without the complexity they do not yet need.
Current Is Not the Right Fit If:
You need a credit building tool integrated with your bank. Current has no credit product. Chime's Credit Builder or a standalone secured card from a credit union is a better path if credit building is a priority alongside banking.
You are optimizing for the highest savings yield. Current's savings rate should be compared to current competitors before choosing it as a savings vehicle. SoFi with direct deposit or a dedicated high-yield savings account may offer more.
You deposit cash regularly. The same cash deposit friction that affects all neobanks applies to Current -- inconvenient and often fee-bearing at retail partners.
You want a single platform for banking, investing, and lending. Current is banking only. Users who want broader financial integration will need to supplement with other platforms.
Build a Banking Structure That Works
Current is one option in a broader digital banking landscape. The FinTech & Modern Money Tools hub covers how to evaluate neobanks, how to structure multiple accounts for maximum function, and how to decide which institution belongs in each role of your banking system.
Explore the FinTech & Modern Money Tools Hub →Frequently Asked Questions
Is Current a real bank? Current is a financial technology company, not a bank. It delivers banking services through partner banks -- Choice Financial Group and Cross River Bank -- both of which are FDIC insured. Your deposits are federally insured up to $250,000 through those institutions. Current does not hold a bank charter of its own.
How do Current's savings pods work? Savings pods are separate, labeled savings buckets within your Current account. You can have up to three pods, each named for a specific goal -- emergency fund, vacation, car maintenance, and so on. Each pod earns interest on its balance independently. You transfer money into pods manually or set up automatic transfers. The pods structure lets you see your progress toward each goal separately rather than tracking a combined savings balance.
How does Current's Overdrive feature work? Overdrive provides fee-free overdraft coverage of up to $200 for qualifying Current members who receive regular direct deposits. The specific amount available to each member is determined by their account history and deposit patterns. When your balance goes negative on a covered transaction, the overdraft is recovered from your next deposit without a fee. Overdrive requires active direct deposit to activate and maintain.
How does Current compare to Chime? Both are fee-free neobanks with early direct deposit and overdraft protection. Key differences: Chime offers a Credit Builder secured card for credit building -- Current does not. Chime has a larger ATM network (60,000 vs Current's 40,000). Current's savings pods offer goal-labeled buckets that Chime's savings account does not. Current's Overdrive coverage ceiling is higher than Chime's SpotMe starting limit. Neither consistently leads the other in savings APY -- compare current rates at the time of your decision.
Should I use Current as my only bank account? As with all neobanks, the PersonalOne recommendation is to maintain a backup account at a credit union or traditional bank regardless of which digital platform you use as primary. Account holds and platform disruptions are not unique to any single neobank -- they are an industry-wide pattern. A backup account that remains accessible during any disruption is straightforward insurance against a temporary problem becoming a real financial crisis.
Resources
- Current -- Official Banking Products Page
- FDIC -- Deposit Insurance Information
- CFPB -- Bank Accounts and Services
- Federal Reserve Bank of St. Louis (FRED) -- Federal Funds Rate Historical Data
Continue Learning About Modern Banking Tools
Current is one piece of a larger banking and FinTech toolkit. The complete framework for evaluating neobanks, budgeting apps, and robo-advisors is in the FinTech & Modern Money Tools guide.
Disclaimer: This review provides independent educational information about Current's products and features. PersonalOne is not an affiliate of Current and has not received compensation for this review. Product features, APY rates, and terms referenced in this article are subject to change. Always verify current rates, fees, and terms directly at Current.com before making any banking decision. This content is not personalized financial advice. PersonalOne provides educational content and does not offer personalized financial planning services.