Updated: September 13, 2026
Home › Budgeting & Savings › Spending Control & Expense Management
What You Need to Know
— Having a budget does not automatically mean you control spending. Execution is a separate skill.
— Spending control is about managing fixed costs, variable costs, and discretionary spending as three distinct categories.
— Lifestyle creep is the most common reason budgets that once worked stop working — this cluster shows how to catch and reverse it.
— You do not need to track every purchase. You need a system that makes overspending structurally difficult.
— Spending control is the bridge between having a budget and actually living within one.
Most people who abandon their budget do not abandon it because they cannot do math. They abandon it because the budget does not account for how spending actually happens — impulsively, emotionally, socially, and in small amounts that feel harmless in the moment and devastating at the end of the month.
Budget Foundations gives you the numbers. Budget Structure gives your money a physical home. But neither of those things stops you from tapping the spending account on a Tuesday because you had a bad day, or letting subscription costs quietly double over eighteen months, or spending 30 percent more on food than you realize because restaurant tabs are not on your radar. This cluster picks up exactly where those two leave off.
Spending Control & Expense Management is the cluster that addresses execution. It is the day-to-day layer of the budgeting system — the one that determines whether the plan you built actually holds in real life, month after month, not just in the first excited weeks after setting it up.
Fixed, Variable, and Discretionary: Why the Distinction Matters
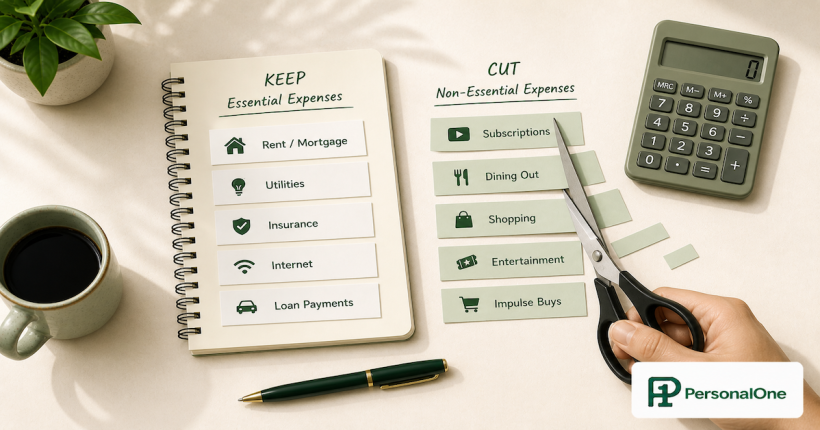
Spending falls into three categories, and they require completely different management approaches.
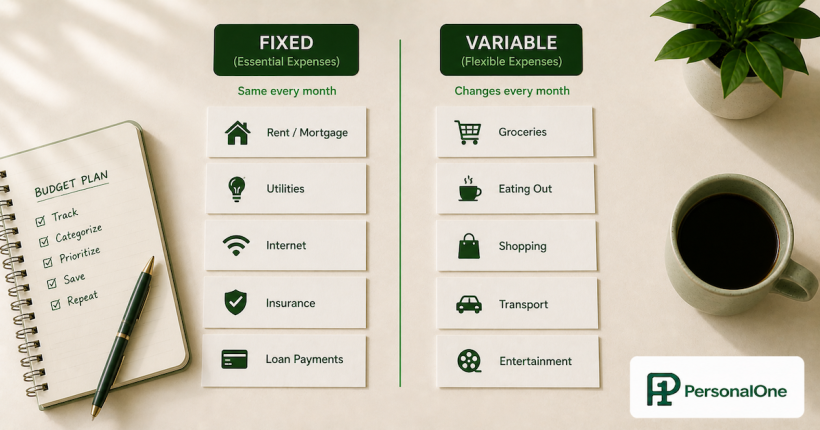
Fixed expenses are the same amount every month — rent, car payments, insurance, loan minimums. You cannot control these in the short term, but you can review them annually and make structural changes when the opportunity arises. Fixing a high fixed expense — refinancing a loan, renegotiating insurance — creates permanent budget improvement that requires no ongoing discipline.
Variable expenses fluctuate month to month but are predictable in category — groceries, utilities, gas. You can set targets for these and hold them, but they require a different approach than fixed costs. Variable expense management is about building category ranges that reflect real life rather than aspirational minimums.
Discretionary spending is the most challenging category because it has no floor and no natural ceiling. Dining out, entertainment, clothing, personal care, impulse purchases — this is where most budgets break down. The articles in this cluster address discretionary spending with structural strategies rather than willpower-based ones.
The Three Categories, Side by Side
Fixed: rent $1,400, car payment $380, insurance $145 — same every month, reviewed annually, not monthly.
Variable: groceries, gas, utilities — a realistic range like $450 to $600, not a fixed target that gets missed every month.
Discretionary: dining out, entertainment, shopping — capped by a fixed account balance, not by remembering to check a running total.
Treating all three the same way, one spreadsheet line each, is why budgets that look complete on paper still break down in practice week after week. Each category needs a different kind of attention, not the same formula applied three times.
Lifestyle Creep: The Silent Budget Killer
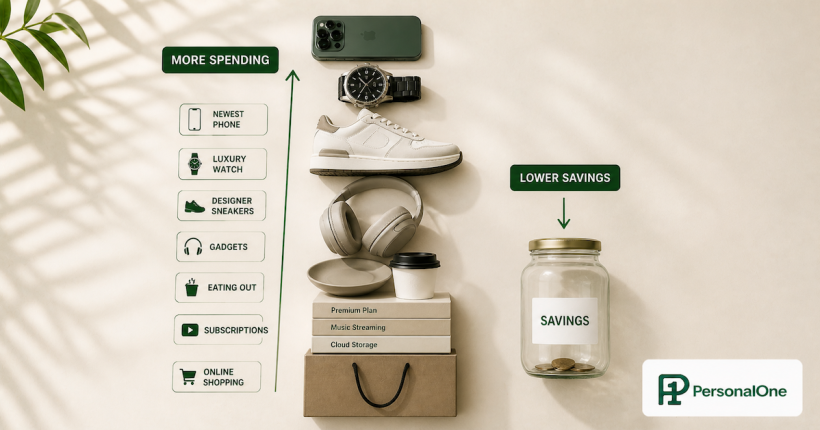
Lifestyle creep is the gradual expansion of spending that follows income increases. A raise arrives. The grocery budget quietly expands. Dining out becomes more frequent. A streaming service gets added. A car upgrade happens. Each decision feels earned and reasonable in isolation. Collectively, they can absorb an entire income increase before a single dollar reaches savings.
The data from the Bureau of Labor Statistics consistently shows that discretionary spending rises proportionally with income for most households — meaning higher earners are not automatically saving more, they are spending more in ways that feel invisible because each individual purchase is affordable.
A $400 monthly raise rarely shows up as one $400 decision. It shows up as five or six smaller ones spread across the following months: a nicer apartment, more frequent takeout, a subscription upgrade, a car payment that crept up at the next lease renewal. None of these individually feels like the moment lifestyle crept in. Collectively, they're exactly that moment, just distributed across enough small decisions that no single one triggers scrutiny.
Lifestyle creep is not inherently wrong. Spending more as you earn more is a reasonable choice. The problem is when it happens by default rather than by decision — when spending expands passively and savings rates stay flat. The articles in this cluster cover how to identify lifestyle creep in your own spending, how to evaluate which upgrades are worth keeping, and how to prevent automatic expansion from consuming budget headroom that should be going toward financial growth.
Expense Management Without Tracking Every Dollar
Tracking every purchase is the most common advice for gaining spending control. It is also the advice most people stop following within a few weeks. Manual tracking is high-friction, time-consuming, and easy to abandon — particularly for variable and discretionary categories where the sheer volume of small transactions makes the process feel punishing.
A more sustainable approach uses structural constraints rather than real-time tracking. When discretionary spending money lives in a separate account with a known balance, the account balance becomes the tracking mechanism. Spending ends when the account is empty, not when the person decides to stop. The structure enforces the budget so the individual does not have to.
Consider the difference in practice. Manual tracking means opening an app or a spreadsheet after every purchase, logging the amount, checking it against a mental running total, for months, indefinitely. Structural control means moving a fixed amount into a spending account on payday and simply not spending once it's gone. The second approach requires one decision, made once, rather than dozens of small decisions made every week.
This cluster covers both approaches: full tracking for the initial data-collection phase, and structural management for long-term maintenance. The goal is to graduate from active tracking to structural control as quickly as possible — because systems that run without effort are systems that actually run.
Expense Auditing: Finding the Money You Did Not Know You Were Spending
One of the most reliable ways to create budget headroom is to audit existing expenses for spending you have forgotten about or no longer value. Subscriptions are the most obvious category: services that were added during a free trial, streaming platforms that rarely get used, app subscriptions that charge annually, and recurring memberships that once seemed worth it and no longer are.
Beyond subscriptions, a thorough expense audit often uncovers category creep in groceries, food delivery, convenience purchases, and recurring charges tied to banking or credit card fees. The articles in this cluster walk through how to conduct a complete expense audit, how to identify which variable costs have drifted above their optimal range, and how to make cuts that hold rather than cuts you reverse within a month.
Two different audit cadences matter here, and they're not interchangeable. A quarterly subscription check catches the digital charges that accumulate fast, free trials that converted, streaming services nobody watches anymore. A once-a-year audit catches the slower-moving costs, insurance, banking fees, memberships, that only shift meaningfully over the course of a year. Running only one of the two leaves real money undiscovered.
Spending Control Is One Layer of a Complete System
Managing day-to-day expenses works best when your budget has a solid foundation and a clear structure behind it. See how every layer connects in the full framework.
Explore the Budgeting & Savings Clusters
Budget Foundations — Where every working budget starts
Budget Structure & Cash Flow — Organize money so it moves without chaos
You are here: Spending Control & Expense Management — Control where money goes day to day
Reviews, Audits & Resets — Fix what breaks and keep the system honest
Savings Strategy & Wealth Growth — Turn your budget surplus into long-term wealth
Money Psychology & Behavior — Understand the habits and beliefs behind your spending
Official Sources
CFPB — Budgeting and Spending Tools
More From This Hub
This cluster is part of the Budgeting & Savings system on PersonalOne — a complete framework for making your budget work in real life, not just on paper.
Go Deeper: Spending Control & Expense Management Guides
This cluster hub covers the framework. For specific situations and step-by-step execution, use these supporting guides:
The Subscription Audit - Coming Soon
Find and cancel the recurring charges quietly draining your budget.
How to catch and reverse lifestyle inflation before it consumes your income growth.
Discretionary Spending Control - Coming Soon
How to manage optional spending without tracking every dollar.
Why Your Grocery Budget Never Works - Coming Soon
The system that fixes the most consistently over-budget category.
The Annual Expense Audit - Coming Soon
How to find hundreds of dollars hidden in your own budget.
What the difference means for your budget and how to manage both.
How to Cut Expenses Without Feeling Broke
A strategic approach to spending reduction that actually holds.
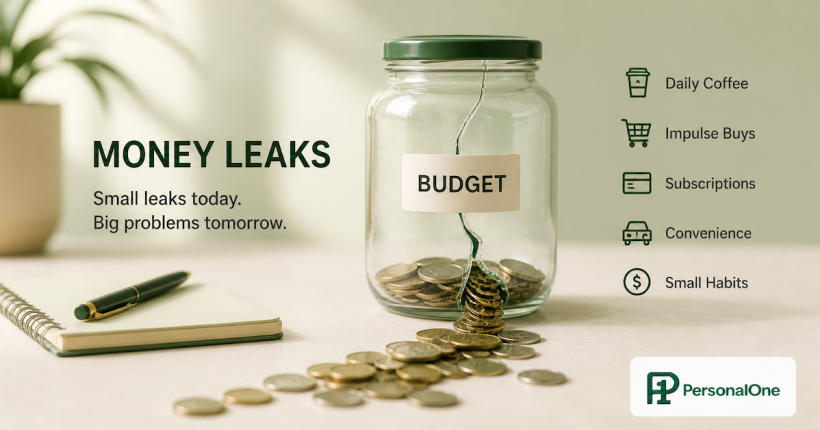
The Biggest Money Leaks Killing Your Budget
Find the Money leaks that drain your budgets and manage them.
Structural fixes that work better than willpower.
How to Reset Your Spending When Things Have Gone Off Track
Spending habits out of control? Reset and fix them with a structural spending system that maintains itself automatically.
Frequently Asked Questions
Do I need to track every purchase to control spending?
Not long-term. Tracking every purchase during the initial foundation phase gives you the data you need to set realistic budgets. After that, structural controls — like keeping discretionary money in a separate account with a known balance — replace active tracking. The goal is a system that manages spending without requiring daily attention.
What is lifestyle creep and how do I know if it is happening to me?
Lifestyle creep is the gradual increase in spending that follows income growth. Signs include: your savings rate has not improved despite income increases, your fixed and variable expenses have grown without a conscious decision to upgrade, and you struggle to identify where money is going despite earning more than before. A spending audit is the fastest way to diagnose it.
What is the difference between variable expenses and discretionary spending?
Variable expenses are necessary costs that fluctuate — groceries, utilities, and gas. They have an essential floor even if the amount changes. Discretionary spending is entirely optional — dining out, entertainment, clothing beyond necessities. Both need management, but the strategies differ because discretionary spending has no natural floor to protect.
How often should I audit my expenses?
A full expense audit is most useful quarterly, aligned with the Reviews, Audits & Resets cluster. A lighter monthly review — checking whether spending accounts are running as expected — is sufficient between full audits. The annual audit is the deepest: reviewing every recurring charge, every subscription, and whether fixed cost structures still make sense.
Is it possible to cut expenses too aggressively?
Yes. Over-restriction is one of the most common reasons budgets fail. When discretionary budgets are cut below a realistic baseline, small deviations feel like budget failures — which leads to abandoning the system entirely. Sustainable cuts are cuts that hold for six months or more without requiring constant willpower to maintain.
Which article in this cluster should I start with?
If lifestyle creep feels like the issue, a raise or two ago without a matching jump in savings, start there. If daily spending feels unpredictable regardless of income, start with discretionary spending control. If you suspect forgotten charges are draining the budget, the subscription and annual expense audits are the fastest path to finding real money without changing a single habit.
PersonalOne Money System
This content is researched, written, and owned by PersonalOne — a free financial education platform built to help Millennials and Gen Z build real financial systems.
This content is for educational purposes only and does not constitute financial advice. PersonalOne is not a licensed financial advisor, broker, or investment professional. Individual financial situations vary — consult a qualified financial professional for personalized guidance.