July, 2026
Home › Financial Automation › Budget Automation Systems › The 15-Minute Weekly Money Review System
TL;DR
— A weekly money review is the human oversight layer that keeps automated budget systems accurate over time — automation handles execution, the weekly review catches what automation cannot.
— The review covers five areas in sequence: account balances, spending category progress, flagged transactions, upcoming scheduled payments, and one forward-looking item — nothing more.
— Fifteen minutes is the correct time boundary — more than 15 minutes signals the review has expanded beyond its purpose into analysis that belongs in the monthly review.
— Most weeks the review produces no action items — that is the correct outcome, not a sign the review is unnecessary.
— The weekly review should be scheduled as a recurring calendar appointment and treated as non-negotiable — the value compounds from consistency over time, not from any individual session.
A weekly money review is the structured human oversight that keeps an automated financial system accurate without turning money management back into a daily task. Automation handles the execution layer — moving money between accounts, paying bills, transferring savings. The weekly review handles what automation cannot: catching categorization errors, identifying unusual transactions, spotting spending category drift before it compounds into an end-of-month surprise, and confirming that the automated transfers that should have fired actually did.
The boundary that makes the weekly money review work is strict time limitation. Fifteen minutes. Not twenty-five. Not an hour of analysis. Fifteen minutes covers the five check items that matter every week without expanding into the deeper review and adjustment work that belongs in the monthly session. This article covers the exact five-item review sequence, the decision rules for each item, and the discipline framework that keeps the weekly review useful rather than either neglected or overextended.
The weekly review is one component of the budget automation systems framework — the recurring human check that maintains the automated system rather than replacing it.
Why Automated Budgets Still Need a Weekly Human Check
A fully automated budget system handles execution without human input under normal conditions. But normal conditions produce exceptions on a regular basis. A bill amount changes by $12. A subscription renews at a higher rate than last year. A savings transfer fires on the wrong date because payday shifted. A merchant categorizes incorrectly and the spending data shows an anomaly that the automation cannot self-correct. A fraud charge appears on a connected card.
None of these exceptions break the automated system permanently. But each one produces a small inaccuracy that compounds over weeks if it is not caught and corrected. A $12 bill increase that goes unnoticed for three months means the essentials account received $36 less than the bills required — a small deficit that accumulates until a payment fails or an overdraft occurs. A miscategorized merchant that goes uncorrected for four months produces spending data that makes the dining out category appear under budget while the actual overspending is hidden in a miscellaneous category.
The weekly review is the mechanism that catches these exceptions before they compound. Fifteen minutes per week prevents the hours of reconstruction and correction that accumulate when automated systems run unmonitored for months.
The Five-Item Weekly Review Sequence
The weekly review covers five items in sequence. Each item has a defined scope and a clear decision rule. Staying within the defined scope of each item is what keeps the review at 15 minutes rather than expanding into an unstructured analysis session.
1Account Balance Check — 3 minutes
What to look at: Current balance of each account against expected balance given the point in the spending period. Essentials account balance against known upcoming autopayments. Lifestyle account balance against expected remaining days in the period. Savings account balance against last week's balance to confirm the automated transfer executed.
Decision rule: If all balances are approximately where they should be given the current date and the automated transfer schedule, no action is required. If a balance is significantly lower than expected, identify whether a transfer did not execute or an unusual charge appeared — this triggers item 3 in the sequence.
What to skip: Do not analyze why balances are what they are. Do not project end-of-month balances. Do not calculate whether you are ahead or behind budget for the month. That is monthly review work. This check is a snapshot comparison against expectation — not an analysis.
2Spending Category Progress — 4 minutes
What to look at: Current spending total in each variable category against the monthly budget allocation, scaled to the current point in the month. If it is the third week of a four-week month, 75 percent of the budget allocation should be used or less. If dining out has consumed $210 of a $220 monthly budget at day 18 of 30, a decision needs to be made before the remaining 12 days arrive.
Decision rule: If all variable categories are on track relative to the proportion of the month that has passed, no action required. If one category is ahead of pace — consuming more than its proportional share of the monthly allocation — make a spending adjustment for the remainder of the month. Note this in a simple tracker for the monthly review to determine if it is a recurring pattern requiring an allocation adjustment.
What to skip: Do not review fixed expense categories — those are automated and will not have unexpected variations. Do not deep-dive into transaction-level detail for categories that are on track. The goal is to identify which categories need attention, not to audit every transaction in every category every week.
3Flagged Transaction Review — 3 minutes
What to look at: Any transaction automatically flagged during the week for being above the threshold amount (typically $150 to $200). Any transaction that appears in an unexpected category. Any charge from an unrecognized merchant. Any duplicate charge that should not have posted twice.
Decision rule: For correctly categorized flagged transactions, confirm the purchase was intentional and move on. For miscategorized transactions, correct the category and create or update the merchant rule so future transactions categorize correctly. For unrecognized charges, investigate immediately — unrecognized charges above $20 should be verified against receipts or contacted with the financial institution the same day.
What to skip: Do not review every transaction for every account. The flagging system exists precisely to avoid this. The only transactions that require weekly review are the ones the system surfaced through alerts and flags. Unflagged transactions in correct categories need no weekly attention.
4Upcoming Scheduled Payments — 2 minutes
What to look at: Any automated payment scheduled to execute in the next seven days. Confirm the account it draws from has sufficient balance to cover it without overdraft. Note any payment that is variable in amount — utilities, credit card statements — to check whether the amount being drawn matches the expected bill amount.
Decision rule: If all scheduled payments have sufficient funding and the amounts are expected, no action required. If a payment is larger than expected — a utility bill that ran higher than usual, a credit card statement that reflects an unusual month — note it and determine whether the essentials account needs a supplemental transfer before the payment date.
What to skip: Do not review payments scheduled more than seven days out. That is next week's check. The seven-day window is short enough to identify funding issues before they become missed payments but long enough to provide time to act if a transfer is needed.
5One Forward-Looking Item — 3 minutes
What to look at: One item from the following week that requires financial preparation. An irregular expense arriving next week that the sinking fund needs to fund. A subscription renewal date that should be reviewed before it autopays. A paycheck due date that is different from the usual schedule and affects upcoming automated transfers. A planned purchase above $100 that has not been accounted for in the current category balances.
Decision rule: If no forward-looking items require preparation, note that the week ahead looks clean and close the review. If one item requires action — a sinking fund transfer, a subscription cancellation before renewal, a budget reallocation before a large planned purchase — schedule it in the calendar immediately before closing the review.
What to skip: Do not plan for items more than seven to ten days ahead. Those belong in the monthly review or in a longer planning session. The forward-looking item in the weekly review is specifically the next seven days — one specific thing, one scheduled action if needed.
When to Expand Beyond 15 Minutes — and When Not To
The 15-minute boundary is a discipline tool, not a rigid rule. There are legitimate reasons the weekly review occasionally runs longer. Identifying a potential fraud charge requires immediate investigation that cannot be deferred to stay within the time limit. A savings transfer that did not execute needs to be traced and corrected the same session. A bill amount that increased requires researching the new amount and updating the automation rule. These are exceptions that warrant the extra time they require.
What the 15-minute boundary prevents is the more common expansion pattern: the review starts with the five-item sequence and then drifts into broader financial analysis. Reviewing investment account performance. Calculating net worth changes since last month. Planning major financial decisions. Comparing this month's spending to the same month last year. These are worthwhile activities that belong in a separate dedicated session — not in the weekly review. When the weekly review expands to include them, it becomes a variable-length activity that is harder to schedule consistently and easier to defer.
The weekly review that consistently takes 12 to 15 minutes produces more value over a 12-month period than the comprehensive weekly analysis session that happens eight times out of twelve because it is too burdensome to complete every week. Consistency is the value. Time discipline is what enables consistency.
How to Schedule the Weekly Review So It Actually Happens
The weekly review that produces the most consistent results is scheduled at the same time on the same day every week and treated as a non-negotiable calendar appointment. The exact day and time matter less than the consistency. Sunday evening works well for many people because it provides a clear financial picture before the new week begins. Friday morning works well for others because it closes the spending week with a review before the weekend. The right choice is the time slot where 15 uninterrupted minutes can be consistently protected week after week.
Setting the recurring calendar appointment with a specific location — the same chair, the same device, the same app open — reduces the friction of starting. The review begins when you open the app or dashboard, not when you decide to open it. The decision to review has already been made by the calendar. The appointment is the commitment. The opening of the dashboard is the execution.
For the weeks where the scheduled time is genuinely unavailable — travel, illness, a unusually demanding week — move the review to the nearest available 15-minute window rather than skipping it entirely. A review that happens on Thursday instead of Sunday still catches the week's flags, confirms the upcoming payments, and checks the category balances. A skipped review allows two weeks of exceptions to accumulate before the next session.
The Relationship Between the Weekly Review and the Monthly Review
The weekly review and the monthly review serve different functions and should not be confused or combined. The weekly review is operational — it confirms the automated system executed correctly, catches exceptions, and makes minor adjustments to keep the week ahead on track. The monthly review is strategic — it evaluates whether the budget allocations are accurately calibrated to actual spending patterns, assesses savings progress against goals, and makes structural adjustments to the automated system based on what the previous month's data revealed.
Information flows from the weekly review into the monthly review. Spending categories that ran ahead of pace in multiple weekly checks are candidates for allocation adjustment in the monthly review. Flagged transactions that revealed a pattern — a subscription that consistently costs more than budgeted, a merchant that repeatedly miscategorizes — become agenda items for the monthly review session. The weekly review feeds the monthly review with specific, actionable data rather than requiring the monthly review to start from scratch with four weeks of unreviewed history.
For variable income earners running the floor-based budget and income smoothing system, the weekly review includes one additional item: smoothing account balance relative to the surplus protocol threshold. If the smoothing account is approaching the threshold where surplus distribution is triggered, the weekly review is where that is noted so the monthly review can execute the surplus protocol on schedule. The full variable income automation structure is covered in the budget for irregular income guide.
What a Healthy Weekly Review Outcome Looks Like
The most common concern people express about establishing a weekly review routine is that they will not know what to do if everything looks fine. This concern reflects a misunderstanding of what the review is designed to produce. Most weeks, a well-running automated budget system will produce a review outcome where all five items show no issues requiring action. All balances are on track. All categories are within pace. No flagged transactions require attention. No upcoming payments have funding gaps. No forward-looking items require preparation.
That outcome — the clean review that requires no action — is not a sign the review was unnecessary. It is confirmation that the automated system is running correctly and that the exceptions the review was designed to catch did not occur this week. The value of the review is not in the corrections it triggers but in the confidence it produces. Knowing that the system was checked and confirmed clean is itself a financial outcome — it removes the background anxiety that accumulates when money is managed on autopilot without any human verification.
The review sessions where action is required — where a flag reveals a charge to dispute, where a category shows it needs a mid-month adjustment, where an upcoming payment needs a supplemental transfer — are where the 15 minutes produces direct financial value. But those sessions produce that value only because the consistent no-action reviews have kept the system calibrated and the exceptions visible when they do occur. The how to automate a monthly budget guide covers how this weekly review fits into the complete automation framework that runs the financial system between review sessions.
15 minutes a week. A financial system that runs all the other minutes.
The weekly review is the human layer that keeps automation accurate. The complete Budget Automation Systems framework covers the automated layer that makes 15 minutes of weekly oversight sufficient.
Explore Budget Automation Systems →Resources
CFPB — Track Your Spending With This Easy Tool
CFPB — Budget Worksheet and Planning Tools
Continue Learning About Financial Automation
This article covers the weekly review system that maintains automated budget accuracy. The complete framework for the automated financial system the weekly review monitors is in the Financial Automation authority hub.
Frequently Asked Questions
What is the best day of the week to do the money review?
The best day is the one where 15 uninterrupted minutes can be consistently protected week after week. Sunday evening is effective for many people because it provides a clear financial picture before the new week begins and the review informs any spending decisions for the coming days. Friday morning works well for people who prefer to close the week with a review before the weekend. The specific day matters significantly less than the consistency of the schedule.
What if I miss a week?
Do the review as soon as the next available 15-minute window exists — do not wait until the scheduled day the following week. A one-week gap means two weeks of transactions, flags, and balance changes to review. While not ideal, catching up within a day or two of the missed session prevents the gaps from compounding into a month of unreviewed history. Set the next scheduled review as normal and continue the cadence from there.
Is 15 minutes really enough?
For a well-configured automated system with active alerts, yes — 15 minutes covers the five review items with time to spare in most weeks. The sessions that run longer are almost always ones where a flagged transaction requires investigation or a category adjustment triggers a broader question about budget allocation. When the review consistently runs longer than 15 minutes on routine weeks, it is usually a sign that the automated category rules are under-configured and generating too much manual review work, or that the review has expanded to include monthly-review work that should be separated.
What tool should I use to run the weekly review?
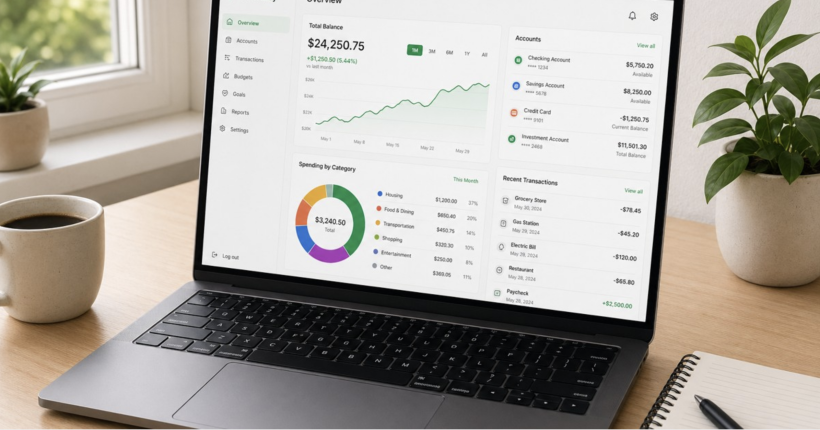
Whatever tool aggregates all connected accounts in a single view and shows spending by category against budget allocations in real time. The specific app matters less than having all accounts visible in one place. Running the review across multiple separate bank apps and credit card portals defeats the purpose — it turns a 15-minute structured review into a 45-minute multi-platform check that is harder to complete consistently.
How does the weekly review differ from the monthly review?
The weekly review is operational: confirm execution, catch exceptions, make minor adjustments. It does not change budget allocations, evaluate savings rate adequacy, or make structural decisions about the automated system. The monthly review is strategic: evaluate whether allocations match actual spending patterns, assess savings progress against goals, and make structural adjustments based on what the month's data revealed. The weekly review feeds data into the monthly review — it does not replace it.
What should I track from week to week to make the monthly review more useful?
Keep a simple running note — a notes app, a document, a physical notepad — with one line per week: the date, any category that ran ahead of pace, any flagged transaction that was corrected, and any action item that was scheduled. Four weeks of these one-line entries gives the monthly review a clear agenda rather than requiring reconstruction of what happened from memory or from transaction-level review. The note takes 30 seconds to write at the end of each weekly session and saves 10 to 15 minutes of reconstruction work at the start of each monthly review.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Budget review practices, automated system configurations, and financial management approaches vary by individual situation and financial complexity. PersonalOne is not responsible for decisions made based on this content.